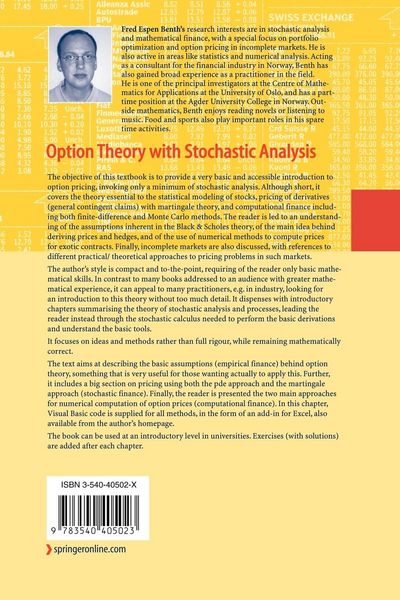
• Produktbild: Option Theory with Stochastic Analysis
  • Produktbild: Option Theory with Stochastic Analysis

Option Theory with Stochastic Analysis An Introduction to Mathematical Finance

Aus der Reihe Universitext

59,99 €

inkl. gesetzl. MwSt., Versandkostenfrei


Beschreibung

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

26.11.2003

Abbildungen

X, 162 p. 1 illus.

Verlag

Springer Berlin

Seitenzahl

162

Maße (L/B/H)

23,5/15,5/1,1 cm

Gewicht

283 g

Auflage

Softcover reprint of the original 1st edition 2004

Sprache

Englisch

ISBN

978-3-540-40502-3

Beschreibung

Rezension

From the reviews:


"This is a … book concerned solely with describing the mathematics of option pricing and I found it a delight to read. It is very well written, quite comprehensive and non-rigorous so that it can be used on courses aimed at a variety of students. … The book includes a healthy number of exercises and there are fully worked solutions to most of these." (David Applebaum, The Mathematical Gazette, Vol. 90 (517), 2006)


"The book provides an introduction to the basic ideas of the mathematical theory of financial options valuation, or, more concretely, to the Black-Scholes theory of pricing contingent claims on equity. … The text is a brief, neat, carefully written introduction to the fundamentals of the mathematics and the modelling of the analysis of options pricing." (José Lúis Fernandez Perez, Zentralblatt MATH, Vol. 1042 (17), 2004)

Produktdetails

Einband

Taschenbuch

Erscheinungsdatum

26.11.2003

Abbildungen

X, 162 p. 1 illus.

Verlag

Springer Berlin

Seitenzahl

162

Maße (L/B/H)

23,5/15,5/1,1 cm

Gewicht

283 g

Auflage

Softcover reprint of the original 1st edition 2004

Sprache

Englisch

ISBN

978-3-540-40502-3

Herstelleradresse

Springer-Verlag KG
Sachsenplatz 4-6
1201 Wien
AT

Email: ProductSafety@springernature.com

Noch keine Bewertungen vorhanden

Verfassen Sie die erste Bewertung zu diesem Artikel

Helfen Sie anderen Kundinnen und Kunden durch Ihre Meinung.

Kundinnen und Kunden meinen

Bewertungen (0)

  • Produktbild: Option Theory with Stochastic Analysis
  • Produktbild: Option Theory with Stochastic Analysis
  • 1 Introduction.- 1.1 An Introduction to Options in Finance.- 1.2 Some Useful Material from Probability Theory.- 2 Statistical Analysis of Data from the Stock Market.- 2.1 The Black & Scholes Model.- 2.2 Logarithmic Returns from Stocks.- 2.3 Scaling Towards Normality.- 2.4 Heavy-Tailed and Skewed Logreturns.- 2.5 Logreturns and the Normal Inverse Gaussian Distribution.- 2.6 An Alternative to the Black & Scholes Model.- 2.7 Logreturns and Autocorrelation.- 2.8 Conclusions Regarding the Choice of Stock Price Model.- 3 An Introduction to Stochastic Analysis.- 3.1 The Itô Integral.- 3.2 The Itô Formula.- 3.3 Geometric Brownian Motion as the Solution of a Stochastic Differential Equation.- 3.4 Conditional Expectation and Martingales.- 4 Pricing and Hedging of Contingent Claims.- 4.1 Motivation from One-Period Markets.- 4.2 The Black & Scholes Market and Arbitrage.- 4.3 Pricing and Hedging of Contingent Claims X= f(S(T)).- 4.4 The Girsanov Theorem and Equivalent Martingale Measures.- 4.5 Pricing and Hedging of General Contingent Claims.- 4.6 The Markov Property and Pricing of General Contingent Claims.- 4.7 Contingent Claims on Many Underlying Stocks.- 4.8 Completeness, Arbitrage and Equivalent Martingale Measures.- 4.9 Extensions to Incomplete Markets.- 5 Numerical Pricing and Hedging of Contingent Claims.- 5.1 Pricing and Hedging with Monte Carlo Methods.- 5.2 Pricing and Hedging with the Finite Difference Method.- A Solutions to Selected Exercises.- References.